Wednesday, October 21, 2026

Indonesia’s Nickel Downstreaming: What a Decade of Industrial Policy Actually Produced

Robert Sterling – AsiaPresswire – Indonesia banned the export of unprocessed nickel ore in January 2020, pulling forward a deadline that had originally been set for 2022. Five years on, it is the most consequential industrial policy experiment in Southeast Asia, and the clearest test anywhere of whether a commodity-producing country can force its way up the value chain by legislating against its own exports.

The answer is genuinely mixed, and the mix is more instructive than either the celebratory or the dismissive version of the story. Indonesia did build a processing industry that did not exist. It also created chronic global oversupply, locked itself into a technology and capital structure it does not control, and discovered that banning an export is much easier than capturing the margin that sits at the end of the chain.

This piece is about what the policy actually built, what it cost, where the money actually goes, and what a company deciding whether to commit capital there needs to test before it writes a cheque.

The policy, stated precisely

The measure most people mean by “downstreaming” is a prohibition on exporting nickel ore, introduced through a mineral and coal mining regulation and brought forward to take effect in January 2020. The logic was straightforward: if ore cannot leave, processors must come to the ore.

Three things about it are worth being precise about, because the shorthand versions mislead.

It is not a tax. It is a prohibition. That distinction matters for modelling, because a tax can be priced and hedged while a prohibition reorders the physical geography of an industry.

It is not limited to nickel. Indonesia has applied the same logic to bauxite and has extended the approach, in various forms, to other commodities including copper and tin. Companies treating this as a nickel-specific rule are reading the policy too narrowly.

It is not static. Thresholds, permitted product forms, royalty structures, and domestic-market obligations have been adjusted repeatedly since 2020. Any model built on the rules as they stood in a given year needs re-checking against the rules as they stand now.

The instrument has also been paired with inducements: tax holidays, investment allowances, and the designation of industrial estates where processing is concentrated. The two largest are the Morowali industrial park on Sulawesi and the Weda Bay complex on Halmahera in North Maluku. Most of the country’s processing capacity sits inside those two sites, which is itself a concentration risk worth naming.

What the country actually became

On the narrow question of whether the policy worked as industrial policy — did processing capacity appear? — the answer is unambiguously yes.

Indonesia moved from exporting raw ore to exporting ferronickel, nickel pig iron, matte, mixed hydroxide precipitate, and, further along, nickel sulfate and precursor material. By the middle of the decade it accounted for a share of global mined nickel supply approaching or exceeding half, depending on the year and the source consulted, up from a fraction of that before the ban. Export revenue from nickel products rose from low single-digit billions of US dollars in the ore era to tens of billions afterwards — a genuine, large, and fast shift in the composition of the country’s exports.

Employment at the two main parks runs to tens of thousands of direct jobs. That is a real number in a country where the alternative use of remote land in Sulawesi and Halmahera was close to nil.

What is less often stated precisely is what that capacity is for. The overwhelming majority of Indonesian processing capacity was built for stainless steel — ferronickel and nickel pig iron feeding the stainless chain — rather than for batteries. The battery-grade portion, produced mostly through high-pressure acid leaching into mixed hydroxide precipitate and then into sulfate, is real and growing but remains the smaller part of the complex. A country that banned ore exports to serve the electric vehicle revolution ended up, in its first phase, mostly serving stainless steel.

Where the chain actually stops

Stage What it produces Where Indonesia sits What it captures
Mining Laterite and saprolite ore Dominant global position Lowest margin, highest physical footprint
Smelting (RKEF) Ferronickel, nickel pig iron Very large, largely built Commodity margin, tied to stainless demand
Refining (HPAL) Mixed hydroxide precipitate Growing, capital-intensive Higher margin, exposed to cobalt and acid costs
Sulfate and precursor Battery-grade nickel chemicals Present but limited Approaching cell-grade pricing
Cathode and cell Cathode active material, cells Early / under construction The margin everyone wants
Pack and vehicle Battery packs, EVs Assembly only The margin downstreaming was aimed at


The table is the argument. Indonesia is unambiguously dominant at row one, very strong at row two, present at row three, limited at row four, and not yet established at rows five and six. The stated ambition of the policy was row six. The delivered result, five years in, is mostly rows one to three.

This is not a criticism of execution so much as a description of what happened. Each step up the table requires a different input — not more ore, but technology, process know-how, qualification with cell makers, and access to a customer who will accept your material into a battery supply chain. Those are not things a prohibition on ore exports can compel. They have to be bought, licensed, or built over years.

The stainless anchor, and why it still sets the floor

Battery demand gets the attention, but stainless steel still absorbs the majority of primary nickel, and that fact is what makes the Indonesian build-out financially legible at all. RKEF lines producing ferronickel and nickel pig iron have a customer base that exists today, in volume, and does not require qualification. That is why the first phase of downstreaming went there rather than into battery chemicals: the capital was available, the technology was mature, the off-taker was known, and the product could be sold the day the line started.

This has a stabilising effect that is easy to miss. When battery-grade nickel prices weaken or when a cell maker delays a programme, the stainless chain keeps absorbing metal. It acts as a floor under offtake, and therefore under utilisation, in a way that a purely battery-facing industry would not have. It also means that the economics of most Indonesian capacity are driven first by stainless demand in China and India and only second by electric vehicle forecasts — which is the opposite of the framing most coverage uses.

The consequence for anyone modelling this market is that “nickel demand” is not one number. It is two largely separate demand pools with different price sensitivities, different customers, and different contract structures, connected mainly by the fact that producers can switch some capacity between them. Treating them as a single market is why so many forecasts of the 2021–2023 period were wrong in the same direction.

What it cost

The costs are real and they fall in four places.

Capital. Smelting and refining are among the most capital-intensive industrial activities in the commodity world. A rotary kiln–electric furnace line is expensive; a high-pressure acid leach plant is more expensive still, and its economics depend on ore grade, acid supply, and the cobalt credit in the byproduct stream. The billions of dollars invested came overwhelmingly from foreign capital, and the single largest source of that capital is Chinese.

Power. Indonesian smelting is heavily coal-fired, with captive power plants built alongside the lines. That has two consequences. The carbon intensity of the resulting nickel is high, which increasingly matters for buyers who have to report it. And it ties the economics of the metal to the cost and availability of domestic coal, which the government also prices and regulates.

Environment. Laterite mining clears land and moves very large volumes of material. The tailings question is the hardest one, and in parts of the country the practice of disposing of tailings at sea has drawn sustained criticism. Acid leaching creates its own waste stream. Companies sourcing Indonesian nickel and reporting against European battery or supply-chain due diligence rules should assume these issues will be raised, and should have sourcing documentation that withstands it.

Market structure. This is the cost that was least anticipated. Indonesia added processing capacity faster than global nickel demand grew. The result, visible through 2023 and into the following years, was sustained oversupply and a nickel price that fell well below the level at which the newest and highest-cost capacity is comfortable. Parts of the industry outside Indonesia — Australian laterite operations and several projects elsewhere — were squeezed or shut. Then the pressure came home: margins inside Indonesia compressed as well.

The part the brochures skip: who captures the margin

A prohibition on ore exports guarantees that processing happens in the country. It does not guarantee that the profit from processing accrues to the country or to its companies.

The ownership structure of much of the built capacity is foreign. Offtake is frequently tied to the same groups that provided the capital. Financing, engineering procurement, and construction were largely supplied from outside. In that arrangement, Indonesia receives employment, taxes and royalties, the depreciation of a large physical asset base, and the strategic position of being indispensable to a critical supply chain. Those are not nothing — employment and fiscal receipts are the point of industrial policy — but they are not the same as capturing the margin at the cell and vehicle end of the table.

There is a second-order effect here that deserves attention. Because the dominant capital and offtake relationships run through Chinese groups, Indonesian nickel has become entangled in the classification rules of other countries’ industrial policy. The United States clean-vehicle credit regime applies foreign-entity-of-concern restrictions that trace ownership and control through the supply chain. European rules apply different but overlapping tests. The practical consequence is that material which is perfectly saleable into one market may be disqualified from another, and the disqualification can be triggered by an ownership stake several levels up rather than by anything about the metal itself.

For a company building a supply chain, this means the question is never simply “is there nickel available in Indonesia.” It is “which corporate entity produced it, who controls that entity, and where does the resulting material qualify.”

Qualification: the step nobody budgets for

Selling metal is one thing. Selling metal into a battery supply chain is a different and much slower business, and the gap between the two is where a great deal of announced capacity quietly stalls.

Battery makers do not buy material on specification sheets. They qualify it, plant by plant, through a process that runs from months to well over a year. Samples are produced, cell-level testing is run against cycle life and safety behaviour, the plant’s process control is audited, and the material is then approved against a specific production line. Change the plant, change the process, or in some cases change the ore blend feeding it, and the qualification has to be revisited.

This has three practical implications. First, a refinery that has not been qualified has no battery customer regardless of how good its product is on paper; it can only sell at commodity pricing, which is precisely the margin it was built to escape. Second, the bottleneck is not always chemistry — it is often simply the queue at the cell makers, who can only run a limited number of qualification programmes at once. Third, the value of an existing qualification is high and underappreciated in deal valuations, because it cannot be bought quickly at any price.

There is a related trap on the buying side. A purchaser that signs an offtake for “battery-grade nickel” from a plant under construction is not buying battery-grade nickel; it is buying a schedule, a qualification process, and a set of risks that sit between the two. Contracts that do not distinguish those states — and that do not allocate the cost of a failed or delayed qualification — are the ones that end up in dispute.

What other countries tried, and what happened

Indonesia is not the first country to try this, and the comparison is instructive because the results differ in ways that track the specifics rather than the ambition.

Chile has moved on lithium through a different instrument — a state-participation model for its salt flat operations, with the state taking control or majority stakes in new projects rather than a blanket export prohibition. The approach preserves more room for existing operators and leaves the question of where processing happens partly open. It also moves more slowly.

Guinea holds the world’s largest bauxite reserves and has pushed for domestic alumina refining for years, with results that have been slower and more uneven than Indonesia’s, largely because the capital and infrastructure requirements are less forgiving and the bauxite market is less concentrated.

Zimbabwe and Namibia both moved to restrict raw lithium exports, with Zimbabwe banning unprocessed lithium ore exports. The stated logic is identical to Indonesia’s. The scale of the resulting domestic industry, so far, is not — which is a reminder that a prohibition only works as industrial policy when there is capital ready to build against it and a customer willing to buy the output.

The Philippines is the closest analogue and the most interesting case. It is a large nickel ore producer and has debated an export ban for years without implementing one, which has left it exporting ore into the Indonesian complex it might otherwise have competed with. The comparison suggests that the speed and decisiveness of Indonesia’s move mattered at least as much as the move itself.

Across all of these, the pattern is consistent. Prohibitions work when three conditions hold: the country’s share of supply is large enough that the ban changes global trade rather than just diverting it, capital is available and willing to build on the country’s terms, and there is a market for the processed product that does not require the producer to win a qualification race first. Indonesia had all three for stainless-grade material and only the first two for battery-grade.

Questions companies actually ask

Can we get battery-grade material, or only stainless-grade? Both exist, but battery-grade capacity is the smaller share and is concentrated in specific plants. Qualification with a cell maker is a separate and slower process from buying metal.

Is the ore export ban at risk of being reversed? Treat it as permanent policy direction, not a temporary measure. It has survived changes of administration and legal challenge. Model it as a structural feature of the market.

What happens if the price stays low? Capacity built for a higher price does not disappear; it runs at lower margin, and consolidation follows. For a buyer, low prices are favourable. For an investor, they change the project’s whole return profile, and the projects most exposed are the newest and highest-cost ones.

How do we handle the carbon intensity? You report it. The footprint of coal-fired smelting is materially higher than alternative supply, and buyers subject to reporting obligations should be sourcing data at the plant level rather than the country level.

Does Indonesian material qualify for incentives in our target market? Check ownership and control, not just origin. This is the single most common and most expensive sourcing error in this market right now.

Three ways this resolves

The next five years are genuinely uncertain, and the honest framing is scenario rather than forecast.

Consolidation. Prices stay low enough that marginal capacity stops running, and the industry concentrates into the lowest-cost operators. Indonesia’s position strengthens on volume while its fiscal take per tonne weakens. This is, on present evidence, the path of least resistance.

Escalation. Indonesia moves decisively up the table — cathode, cell, and eventually vehicle assembly, supported by incentives and by requirements attached to domestic market access. This requires technology partnerships and customer qualification that no export rule can mandate. Several projects are aimed at it. Whether they reach commercial scale on schedule is open.

Fragmentation. Buyers in the United States and Europe build qualified supply outside Chinese-controlled chains, while Chinese-linked capacity serves the rest of the market. Indonesian volume keeps growing but splits into two pools with different prices and different customers. Elements of this are already visible.

These are not mutually exclusive. Consolidation and fragmentation can happen at the same time, to different parts of the industry.

Glossary

  • Laterite — The ore type Indonesia mines, requiring different processing from the sulphide ores common elsewhere.
  • RKEF — Rotary kiln–electric furnace, the route to ferronickel and nickel pig iron for stainless steel.
  • HPAL — High-pressure acid leaching, the route to mixed hydroxide precipitate for battery-grade material.
  • MHP — Mixed hydroxide precipitate, the intermediate product that HPAL produces and refiners convert to sulfate.
  • FEOC — Foreign entity of concern, the ownership-and-control test that determines clean-vehicle credit eligibility in the United States.

The risks worth pricing

Technology lock-in. Much of the built capacity was designed around the ore, the capital, and the customer relationships available at the time it was built. If battery chemistry shifts away from high-nickel formulations, that capacity is less valuable than its construction cost.

Environmental liability. Land disturbance and tailings practice are live issues now and will remain so. Expect tightening, and expect the compliance cost to land on producers and then on buyers’ documentation requirements.

Concentration. Two industrial parks carry most of the capacity. A single-site disruption — power, labour, logistics, regulation — is a supply-chain event, not a local one.

Policy drift. Royalty rates, export levies, domestic processing obligations, and local content requirements have all moved. A model built today should be stress-tested against at least two alternative policy settings.

The commodity cycle itself. Nickel is a cyclical commodity with a volatile price history, including a short squeeze in 2022 that remains the clearest illustration of how unstable this market can be. Any project economics built on a spot price rather than a through-cycle assumption should be redone.

A checklist before committing capital

  • Establish which row of the chain you are actually investing in, and whether the margin at that row justifies the capital
  • Trace ownership and control of your counterparty to the level required by your target market’s rules — not to the level that is convenient
  • Source emissions data at plant level, and confirm it survives your reporting obligations
  • Model at least two nickel prices and two policy settings; if the project only works at one, it is not a project
  • Confirm power supply, logistics, and port access are contracted rather than assumed
  • Check whether your offtake customer has already qualified the specific plant, or whether that process has not started
  • Ask what happens to your asset if battery chemistry moves away from high-nickel

The honest bottom line

Indonesia’s nickel policy is neither the triumph its supporters describe nor the cautionary tale its critics prefer. It did the thing it set out to do: it moved processing into the country, created a large industrial base where there was essentially none, and changed the structure of a global commodity market within five years. Very few industrial policies in the developing world have done that much, that fast.

What it did not do is the harder part. Banning an export moves the location of an activity. It does not move the location of the margin, the technology, or the customer relationship — those are earned at the top of the chain, and they are earned by qualification, process capability, and access, none of which respond to a prohibition.

For a company deciding what to do about it, the practical conclusion is unromantic. Indonesian nickel is abundant, cheap, and increasingly central to the world’s battery supply. It is also concentrated, carbon-intensive, policy-exposed, and tangled in other countries’ ownership rules. Those facts are not contradictory. They are the deal, and the companies that do well here are the ones that priced all of them rather than the ones that found the cheapest tonne.


source https://newsroom.seaprwire.com/press-releases/technologies/indonesias-nickel-downstreaming-what-a-decade-of-industrial-policy-actually-produced/

The Payout Problem Nobody Warned Us About: Getting Paid Across Southeast Asia’s QR Rails

Robert Sterling – SeaPRwire – A hotel in Cebu lost a booking last March because of a QR code. Not a broken one — a missing one. A guest from Singapore stood at the front desk with her banking app open, ready to pay, and there was nothing to scan. She paid in cash from an ATM down the road, complained in a review the same evening, and the property’s operations manager spent the next two weeks explaining to ownership why a “cashless” property needed a cash float again.

That is the shape of the problem most Southeast Asian businesses actually have with payments in 2026. It is not fraud, and it is not interchange. It is that the person standing in front of you has already decided how they want to pay, and your checkout was built for a card.

This is a practical guide to the rails that matter, what they cost, how long money takes to arrive, where it gets stuck, and which countries quietly make it hard to take your own money out.

Cards are not the default here

A merchant entering Southeast Asia with Visa and Mastercard acceptance and nothing else has already lost most of the market. Cards account for under 15 percent of potential customers across most ASEAN markets. In Thailand, account-to-account payments make up 44 percent of e-commerce value. In the Philippines, GCash alone has more users than most countries have adults, and GrabPay, GoPay, OVO, DANA, TrueMoney, and Touch ‘n Go each hold meaningful share at home.

The region runs instead on government-built real-time rails and QR standards, and they are not “alternative payment methods” in the way buy-now-pay-later is in Europe. They are the default. Research points to local payment methods representing 69 percent of Asia Pacific e-commerce transaction value by 2028, up from 64 percent in 2023, with non-card wallets reaching 57 percent. The trajectory is away from cards, not toward them.

The reason is partly cultural, but mostly structural. These rails were built by central banks to bring unbanked populations into the financial system, and they priced merchant acceptance at near zero to make that work. A QR payment costs a merchant far less than a card transaction — estimates run 50 to 80 percent lower in acceptance cost — and that pricing floor is very hard for card networks to match.

The five rails that matter

Every market built its own. That is the single most expensive fact in this article.

Market Real-time rail Operator QR standard Settlement
Singapore PayNow (over FAST) ABS / BCS SGQR Near-instant
Malaysia DuitNow (RPP) PayNet DuitNow QR Near-instant
Thailand PromptPay ITMX Thai QR Near-instant
Indonesia BI-FAST Bank Indonesia QRIS Near-instant
Vietnam NAPAS 247 NAPAS VietQR Near-instant
Philippines InstaPay / PESONet BSP QR Ph Instant / same-day


Each has its own integration standard, settlement timing, and local partner ecosystem. An institution offering collections across five markets is not building “an ASEAN offering.” It is building five distinct market capabilities that happen to sit next to each other on the map.

The scale behind these rails is larger than most outsiders assume. Indonesia’s QRIS has passed 56 million users and roughly 38 million merchants. Malaysia’s DuitNow QR doubled to 3 billion transactions. PromptPay carries 74 million registered users and processes over 74 million transactions daily.

Cross-border QR actually works now

The interesting development of the last eighteen months is that these national systems started talking to each other. This is genuinely new, and it changes the calculus for merchants whose customers cross borders.

Cross-border QR payments work through interoperable regional networks. A visitor from Singapore opens a PayNow-enabled banking app, scans a Philippine merchant’s QR code, and approves the payment in SGD from her Singapore account. The merchant receives the equivalent in PHP. The merchant does not need a foreign currency account. There is no currency exchange at the point of sale.

Settlement timing differs from domestic transactions, and it is the detail most merchants get wrong when modelling cash flow: domestic transactions settle next business day in local currency; cross-border QR transactions take longer — typically T+1 to T+2 calendar days depending on the corridor and provider. Plan for that gap during peak tourist periods.

By 2026, cross-border QR was live across Indonesia, Thailand, Singapore, Malaysia, and the Philippines, with more than 30 digital payment schemes supported through shared infrastructure. Singapore’s PayNow also links to India’s UPI. ASEAN had 29 cross-border payment linkages processing 36.2 million transactions worth about USD 716 million in one reported period, and the Regional Payment Connectivity initiative kept adding to that.

Project Nexus — the BIS Innovation Hub scheme operated through Nexus Global Payments in Singapore — was on track for rollout in 2026, connecting the instant payment systems of India, Malaysia, the Philippines, Singapore, and Thailand through a central gateway. If that lands as expected, the plumbing gets materially simpler for anyone serving several markets at once.

The licensing wall nobody budgets for

Here is where optimistic expansion plans usually die. Each market regulates money movement separately, and no regional passport exists.

Market Regulator Representative licence Indicative timeline
Singapore MAS Major Payment Institution ~2 years
Malaysia Bank Negara Malaysia Money Services Business 2+ years
Philippines BSP Remittance & Transfer Company / EMI ~1 year
Indonesia Bank Indonesia Payment Service Provider (PJP) ~2 years
Thailand Bank of Thailand / MoF Designated Payment Service ~3 years
Vietnam State Bank of Vietnam Intermediary Payment Service 3+ years


A licence held in Singapore does not extend to IDR flows in Indonesia or VND collections in Vietnam. For most businesses that means either pursuing local licensing market by market — a multi-year undertaking — or working through local partners, each adding counterparty risk, commercial negotiation, and operational oversight to the stack.

The practical consequence: unless you are a payments company, do not try to hold licences. Use a licensed local provider in each market and accept that you are assembling a patchwork rather than buying a platform.

The trap nobody warns you about: getting your own money out

This is the section most guides skip, and it is where operators lose real money.

Some ASEAN currencies carry capital controls, restricted convertibility, or repatriation rules that do not apply to SGD or USD. The Indonesian rupiah, the Vietnamese dong, and to a lesser extent the Philippine peso and Thai baht all sit somewhere on that spectrum. Funds collected locally cannot always be freely converted and moved out.

Market Convertibility What it means operationally
Singapore Fully convertible Standard FX hedging available, freely deliverable
Malaysia Not internationalised Offshore MYR trading not recognised; FX must transact onshore
Philippines Largely convertible (current account) Deliverable onshore, often hedged via NDF
Indonesia Heavily controlled Onshore rails plus documentation trail for every conversion
Vietnam Non-convertible offshore VND cannot be traded outside Vietnam; FX needs documented purpose


For a business running treasury across several markets, this creates genuine balance-sheet exposure: cash trapped onshore, unpredictable conversion timing, and pressure to accept unfavourable rates to unwind positions quickly. Model this before you open the second market, not after.

Choosing a provider, honestly

The honest answer is that no single platform covers all of ASEAN well, and any vendor that claims otherwise is describing aspirational coverage rather than live capability. What you are really choosing is how much fragmentation you will manage yourself.

The trade-offs worth weighing explicitly: local payment method depth versus breadth of markets; whether the provider holds its own licence or rides on a partner’s; settlement speed and whether it varies by rail; what happens when a transaction fails; and whether reconciliation actually reconciles, which is where operators lose the most staff hours.

A mid-sized regional business typically ends up with two or three providers rather than one. That is not a failure of planning. It is the current shape of the market. The mistake is assuming you can consolidate later without redoing integrations.

Provider type Strength Watch out for
Regional PSP with broad local methods Fastest route to real coverage Settlement varies by corridor; check per-rail terms
Card-first global gateway Familiar integration, strong fraud tooling Thin local rail coverage; poor non-card conversion
Orchestration layer One API across many providers Adds cost; still needs underlying local licences
Local bank acquiring Best pricing on that rail One market only; slow to extend


How this differs country by country

Country-level differences are large enough that a single regional playbook will produce bad decisions.

Indonesia — QRIS is the gravity well, with 56 million-plus users. But IDR is heavily controlled, so plan repatriation before you plan acquisition. Documentation discipline matters more here than anywhere else in the region.

Philippines — Strong English capability makes integration easier, but the payment mix is fragmented across GCash, Maya, QR Ph, InstaPay, and PESONet, plus over-the-counter networks that matter enormously outside Metro Manila. Tourism-facing businesses should treat cross-border QR as baseline, not premium.

Thailand — PromptPay is deeply embedded, and tourists from neighbouring markets increasingly expect to pay through linked rails. Watch household-debt-driven softness in domestic consumption when forecasting.

Vietnam — VietQR is growing quickly, but VND offshore restrictions are the binding constraint. Build the compliance path first.

Malaysia — DuitNow QR doubled to 3 billion transactions. MYR must settle onshore, which shapes treasury design more than most operators expect.

Singapore — The most mature and most expensive. PayNow is table stakes, but Singapore is usually where you incorporate and bank, not where your volume sits.

Mistakes that cost money

Assuming card-first economics still apply. They do not. Budget as though cards are a fallback, because that is what they are for most of your customers.

Modelling cross-border settlement as same-day. It rarely is. That gap shows up as working capital.

Treating one licence as regional. It is not. Every additional market resets the clock.

Ignoring reconciliation until month three. Manual reconciliation across five rails with different reference formats consumes finance headcount faster than any other operational issue here.

Discovering repatriation rules after collecting the money. This is the expensive one.

Questions businesses actually ask

Do I need a local entity to accept payments? Usually not to accept, but often yes to settle directly or to hold a licence. Working through a licensed local provider sidesteps this for most merchants.

Is cross-border QR worth enabling for a small business? If your customers include travellers or overseas buyers, yes — the incremental cost is low and the alternative is losing the sale entirely. The service businesses, tour operators, and boutiques that benefit most are the ones with regular foreign footfall.

Will Project Nexus remove the fragmentation? Not entirely. It meaningfully reduces integration complexity across connected markets, but licences, currency rules, and reconciliation remain local problems.

How long before this is genuinely simple? Realistically, several years at best, and probably not completely.

What the money actually costs, line by line

Most operators budget for a headline transaction fee and get surprised by everything around it. The real cost of accepting a payment in this region has four layers, and only the first appears on the pricing page.

  1. Acceptance cost. This is the merchant discount rate, and it is where local rails win outright. QR acceptance typically runs far below card interchange — the central-bank mandate to serve small merchants with cheap acceptance is why adoption happened at all. Expect QR and real-time transfer costs to sit well under 1 percent at most volumes, against card rates that can run several times that once cross-border and rewards cards are mixed in.
  2. FX spread. If a customer pays in SGD and you settle in PHP, someone converts that money, and the spread is rarely the interbank rate. This is usually the largest invisible cost in a cross-border setup, and it is the one most often quoted as “free” in marketing. Always ask for the spread expressed as a percentage above mid-market, not just whether conversion is available.
  3. Settlement float. Money in transit is money unavailable. If cross-border QR settles T+2 rather than next business day, a business turning over PHP 3 million a month is carrying roughly two days of working capital at all times. That has a financing cost, even if nobody books it as one.
  4. Reconciliation labour. This is the one that quietly dominates for smaller operators. Each rail generates references in a different format, settles on a different schedule, and reports failures differently. A finance officer spending six hours a month per market matching payments is a real cost line, and it scales linearly with the number of rails you accept.

The arithmetic that matters: a merchant paying 0.8 percent on a local rail plus a 1.5 percent FX spread plus two days of float is often paying less than a merchant paying 3 percent on a card with instant settlement — but only if volume is high enough for the float to be forecastable. Below a certain monthly turnover, the slower rail is genuinely worse for cash flow regardless of headline pricing.

A worked example: the tour operator’s cash cycle

Consider a dive operator in Davao taking bookings from Singaporean, Malaysian, and domestic visitors. Before enabling cross-border QR, roughly 40 percent of foreign enquiries that reached the payment stage dropped out — the booking form offered card or bank transfer, and neither matched how the customer habitually paid. Of those lost bookings, the operator estimated that about half were recoverable if the visitor could pay from their home app.

After enabling PayNow, DuitNow, and QRIS acceptance alongside QR Ph for domestic guests, recovery improved, but the cash cycle changed shape. Domestic bookings settled next business day. Cross-border bookings settled on a T+2 calendar-day cycle. For a business whose deposits fund equipment rental and boat fuel before the guest arrives, that two-day gap mattered more than the fee difference — particularly during Chinese New Year and summer peaks, when a week of concentrated bookings could leave several hundred thousand pesos in transit simultaneously.

The lesson generalises: enabling more rails raises conversion and lengthens your cash conversion cycle at the same time. Both effects are real. The mistake is counting the first and discovering the second during your busiest month.

When cross-border QR is not worth enabling

It is not universally the right move, and saying otherwise does merchants a disservice.

Skip or defer it when your customer base is overwhelmingly domestic, when your average ticket is large enough that customers will accept a card or transfer anyway, or when you lack the staff to handle reconciliation across additional rails. A B2B manufacturer invoicing three buyers twice a month does not need five payment methods; it needs reliable settlement on one.

The businesses that clearly benefit are those with regular foreign footfall — tourism-facing retail and F&B in places like BGC, Intramuros, Boracay, and Cebu; export-linked e-commerce selling to Southeast Asian buyers; event and trade-show operators; and service businesses invoicing overseas clients who hold no local bank account. For those, acceptance is increasingly a baseline requirement rather than a premium feature.

Which rail to launch first

Teams routinely ask which single market to integrate first, and the answer is less about market size than about what the first integration teaches you. Start in the market where your own entity already sits, because licence questions, bank onboarding, and FX behaviour are all easier where you already have local standing. Your first integration will surface every gap in your reconciliation tooling, and it is far better to find those gaps somewhere you already understand the language, the banking hours, and the regulator.

Once that first rail is stable, the sequencing that usually works is: add the market sharing the most customers with the first, then the market whose foreign tourists most often appear in your funnel, then everything else. What rarely works is trying to launch three markets simultaneously because regional coverage looks achievable on a provider’s coverage map. Every integration you run in parallel multiplies the number of failure modes you have not yet diagnosed, and it is much harder to tell whether a problem lives in your integration, the provider, or the local rail.

One practical rule worth adopting: do not add a second rail until the first one has run for a full month with clean reconciliation. A single clean month tells you whether your reference formats, failure handling, and payout timing are genuinely working, and that knowledge transfers to the next market with very little adjustment.

Glossary

  • Real-time rail — A national instant payment network operated or overseen by the central bank, moving funds between accounts in seconds.
  • QR interoperability — The arrangement that lets a customer scan a merchant QR using a wallet or banking app from a different country.
  • NDF — Non-deliverable forward, a cash-settled FX derivative used to hedge currencies that cannot be freely delivered offshore.
  • T+2 — Settlement two calendar days after the transaction, as opposed to next business day.
  • PJP / MPI / MSB — Local payment licence categories in Indonesia, Singapore, and Malaysia respectively.

What changes next, and what could go wrong

The direction of travel is toward fewer, better-connected rails. Southeast Asia’s digital payments already crossed USD 1 trillion in transaction value. National QR systems keep growing, and cross-border linkages keep multiplying.

The risks run the other way too. Data localisation requirements are tightening in several markets, which could push against harmonisation. Geopolitical friction affects corridors that currently work smoothly. And the same financial-inclusion mandate that made these rails cheap to begin with could make regulators reluctant to let them become the plumbing for cross-border capital flows.

The practical stance for 2026: build for fragmentation, buy local depth, and keep any single-market integration small enough that unwinding it is survivable.

A checklist you can run this week

  • List the five payment methods your last 100 customers actually tried to use
  • Check whether your current provider settles each rail at the same speed — read the per-rail terms, not the headline
  • Ask your provider directly: which licence do you hold, and whose do you ride on?
  • Model repatriation for your largest non-SGD, non-USD exposure before adding another market
  • Test one cross-border QR transaction end to end with a colleague in another country
  • Count the staff hours spent on manual reconciliation last month

The honest bottom line

The businesses that get this right are not the ones that found a magical all-in-one provider. They are the ones that accepted fragmentation as permanent, built a small set of well-understood integrations instead of one fragile universal one, and got religion about reconciliation and repatriation early.

Getting paid in Southeast Asia in 2026 is genuinely easier than it was three years ago. It is still five problems wearing one regional label, and treating it that way is the difference between money arriving and money sitting somewhere you cannot reach.


source https://newsroom.seaprwire.com/press-releases/finance/the-payout-problem-nobody-warned-us-about-getting-paid-across-southeast-asias-qr-rails/

Tuesday, October 20, 2026

Stop Clicking Dashboards Just Tell the AI What You Want Done

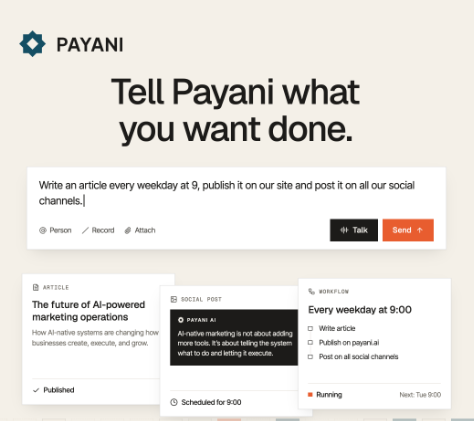
By: James Vance – SeaPRwire – Marketing teams still spend more time wrestling software than closing deals. Dashboards multiply. CRMs demand constant feeding. Email tools sit in separate tabs. Campaign data lives somewhere else entirely. People become the glue holding fractured systems together. That friction is the real cost of modern sales operations. Payani AI just launched a system that flips the model. Users speak or type what they want done. The platform handles the rest using the company’s own data.

The launch centers on a conversational execution layer called Ask Payani. It sits across CRM records, email threads, campaign metrics, and pipeline stages. A user can say: find everyone who replied to last week’s campaign, draft a personal follow-up for each, and book a call with those who asked about pricing. The system identifies the relevant contacts, pulls prior communications, prepares the messages, and coordinates next steps. No separate logins. No manual list building. No switching between apps. The same interface covers prospecting, content production, social publishing, advertising, reporting, and workflow automation. Ali Payani, founder and CEO, put it plainly. Software has always required people to do the connecting and the operating. Payani was built the other way around. The AI already understands the business. You tell it the outcome. It figures out the steps. The company also released Payani Switch to ease migration from HubSpot, Pipedrive, and Zoho. Early users moved more than 100,000 contacts in the first weeks. One team transferred a full HubSpot history of 46,000 contacts in a single afternoon. Every action still passes through existing permissions and validation rules. Users can review proposed messages or workflows before anything goes out. The system records the decisions for accountability. Human control stays in place while the repetitive coordination disappears. Payani AI grew out of Payani Group’s years running marketing and growth operations. The product was developed and funded internally. It is already running inside the group’s own campaigns. Ali Payani is scheduled to deliver a keynote at the 2026 TechEquity AI Summit on the shift from human-operated software to AI-directed operations. The conversational system became available on October 20, 2026. Businesses can examine the full platform at payani.ai.

The practical closed loop is clear. Data, expertise, and execution now live in one environment. A single natural-language instruction can trigger coordinated work across the stack without forcing people to become system administrators. Migration friction drops when contacts and history move in hours rather than months. Oversight remains through review gates and permission structures already familiar to most teams. The endgame is not another chatbot bolted onto existing tools. It is software that absorbs the operational load so marketers and sellers can focus on judgment and relationships. Companies still drowning in tab-switching should test whether a direct instruction can replace the daily dashboard shuffle. That is the only metric that will matter in the next cycle of sales technology.

Author bio: James Vance, long-time senior commentator for international technology weeklies covering enterprise software and AI product strategy.


source https://newsroom.seaprwire.com/press-releases/technologies/stop-clicking-dashboards-just-tell-the-ai-what-you-want-done/

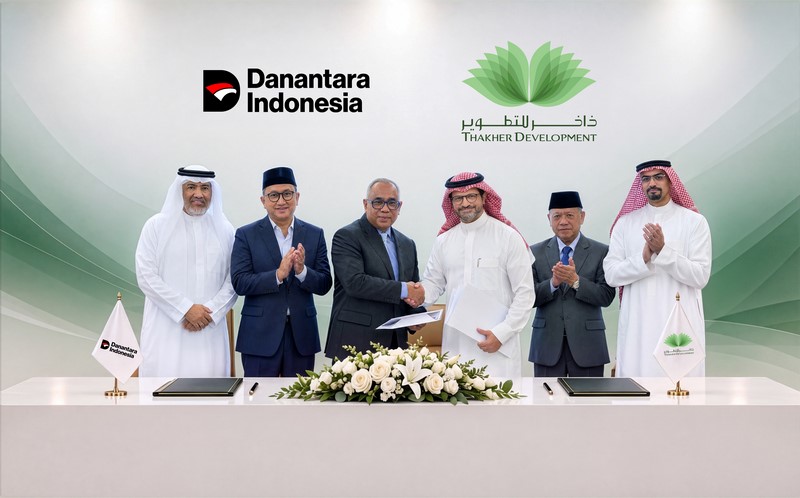
Thakher Development Completes SAR 2B Landmark Handover to Danantara Indonesia in Makkah

Marking a historic milestone for foreign property ownership in Makkah, Thakher Development completes the SAR 2 billion sale of the 1,461-room Novotel Thakher Makkah and 14 development plots to Indonesia’s sovereign wealth fund.

MAKKAH, Saudi Arabia – SeaPRwire –  Thakher Development, the master developer of the Thakher Makkah megaproject, has officially completed the handover of property ownership certificates to Danantara Indonesia, Indonesia’s sovereign wealth fund. The milestone marks one of the first major real estate acquisitions by an international sovereign investor in Makkah, completing Danantara’s SAR 2 billion (approx. US$ 533 million) purchase of the Novotel Thakher Makkah hotel towers and 14 adjoining development plots.

The transaction was made possible by Thakher Makkah’s position as an established, integrated destination 1.2 kilometres north of the Grand Mosque. Spanning 320,000 square metres, with a total investment value of more than SAR 26 billion, Thakher Makkah offers international investors investment-ready lands designated for hospitality and commercial development and operating hotel assets. The destination’s hotels offer about 2,700 rooms and serviced apartments.

The milestone marks a significant step in Saudi Arabia’s opening of Makkah to long-term international investment under the Law of Real Estate Ownership by Non-Saudis, which took effect in January 2026, and supports the Kingdom’s Vision 2030 goal of expanding the capacity and quality of services for pilgrims.

“This is a historic moment for Thakher Makkah. Welcoming a leading international sovereign investor to own property in our destination reflects global confidence in Thakher Makkah, and in the Kingdom’s opening of Makkah to long-term partners who share its commitment to serving the guests of Allah,” said Faisal Shaker, Chief Executive Officer of Thakher Development. “As Thakher Development, we design investment opportunities for partnerships of this scale, and we are proud to have taken this transaction from signature to title in ten months. Our focus now is to ensure that Danantara’s investment ambition and our development strategy align and to help Danantara deliver the next phase, so that more of Indonesia’s pilgrims can remain within reach of the Haram. Today, we have turned this opportunity into a replicable model to serve as the gateway for foreign investors into Makkah.”

For Indonesia, institutional asset ownership replaces decades of renting accommodation one season at a time. Indonesia has the largest Hajj quota of any country, with 203,320 regular places in 2026, and around 1.5 million Indonesians perform Umrah each year. The hotel can accommodate about 4,400 pilgrims per Hajj season.

Rosan Roeslani, Chief Executive Officer of Danantara Indonesia, said, “This milestone represents a concrete step in building a long-term hospitality investment platform in the Kingdom of Saudi Arabia. Our focus is to manage these assets with rigorous investment discipline while developing an integrated ecosystem that enhances the quality of accommodation and services available to pilgrims from Indonesia and around the world. More broadly, this marks the beginning of an extended economic partnership between Indonesia and the Kingdom of Saudi Arabia, and we will continue to deepen our bilateral cooperation by exploring opportunities in Madinah and across other sectors that create shared value for both nations.”

Novotel Thakher Makkah comprises three 19-story towers with 1,461 rooms and suites across about 33,903 square metres, standing as one of the largest Novotel properties globally. Accor will continue to operate the hotel under its existing management agreement.

Danantara plans to develop the 14 plots within Thakher Makkah, totalling 44,088 square metres, into hotels with about 6,000 additional rooms and a shopping mall with more than 90 retail outlets, representing planned investment of more than SAR 2 billion and further expanding the destination’s hospitality and commercial capacity.

For Media Inquires:

Legends PR

PR@Legends.sa

+966559810777


source https://newsroom.seaprwire.com/press-releases/finance/thakher-development-completes-sar-2b-landmark-handover-to-danantara-indonesia-in-makkah/

Monday, October 19, 2026

Hank Robotics Earns Chamber Nod for Drone Cleaning Across Roofs and Towers

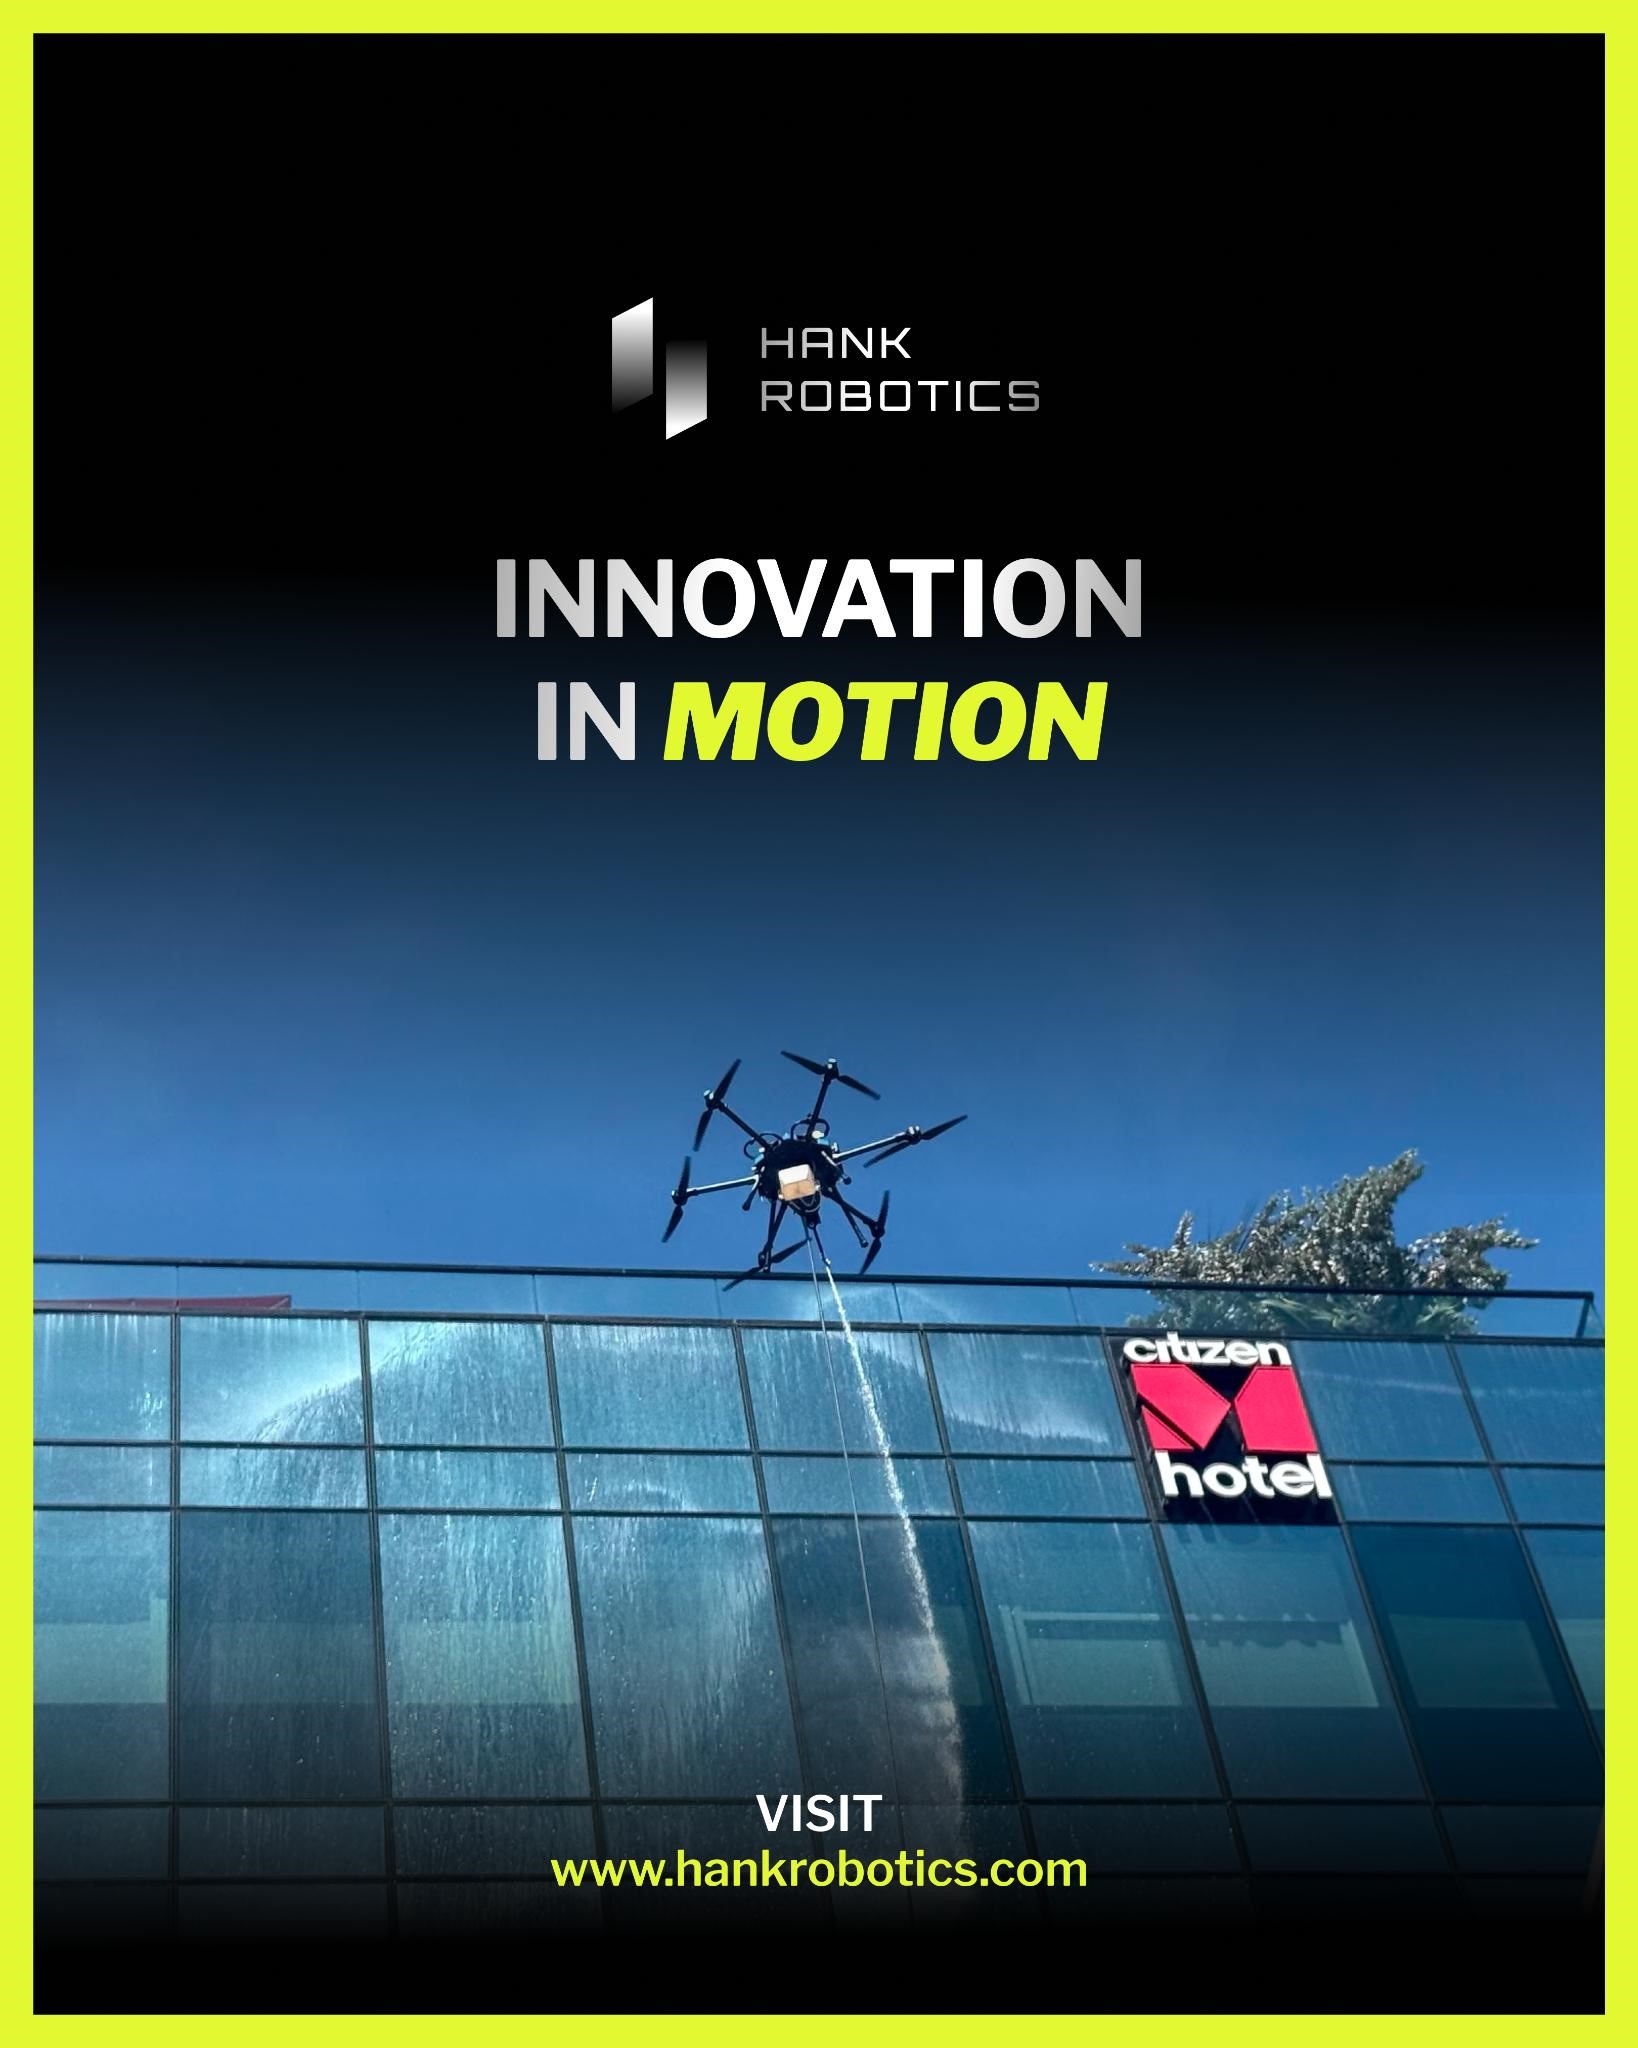
By: TechVanguard – SeaPRwire – Hank Robotics just joined the 2026 U.S. Chamber of Commerce CO-100 list. The Miami firm is one of one hundred recognized American businesses. It sits among the ten Tech Innovators honorees. Founded in 2024, the company uses drones and robotics for commercial exterior work that once needed heavy gear and long setup times.

The service list is concrete. High-rise window cleaning. Commercial roof washing. Façade cleaning. Pressure washing. Soft washing. Solar panel cleaning. Water tower and elevated tank maintenance. Thermal drone inspections. The company pairs drone-assisted methods with conventional techniques. It targets surfaces that are hard to reach. Clients include hotels, office towers, warehouses, shopping centers, industrial sites and property managers. The goal is efficient exterior maintenance with less disruption.

Project numbers appear in the release. Approximately 570,000 square feet of warehouse roof and façade cleaning for H&M. 270,000 square feet of commercial roof cleaning for The Graham Companies. Exterior window work for citizenM Hotels. In Hobbs, New Mexico, about 400,000 square feet of thermal drone roof scanning and leak assessment for the city. Thermal imaging spotted abnormal temperature patterns and possible moisture intrusion. More than 100,000 square feet of cleaning for the DuPage Water Commission in Illinois covered water towers and related infrastructure.

International work is under way. The company is coordinating exterior building cleaning linked to the Central Bank of Barbados’ Tom Adams Financial Centre in Bridgetown. Additional capabilities include commercial building inspections, thermal roof assessments, aerial documentation and preventive maintenance for institutional and industrial properties. On the residential side it offers window cleaning, roof soft washing, house washing, driveway cleaning and paver pressure washing across South Florida. Training programs are also in development. They cover equipment operation, cleaning techniques, safety and the basics of running a commercial drone-cleaning business.

The Chamber recognition highlights the use of drone technology and robotics in maintenance. From Miami high-rises to municipal tanks and an overseas financial centre, the same toolkit is being applied. Scaffolding and extensive planning still exist. Propellers now handle part of the load.

Keep the thermal scan running before the next wash.

Author bio: TechVanguard, social-media tech voice with a large following on X, focused on practical gaps between AI promises and workplace reality.


source https://newsroom.seaprwire.com/press-releases/technologies/hank-robotics-earns-chamber-nod-for-drone-cleaning-across-roofs-and-towers/

Sunday, October 18, 2026

Companies Race Toward Autonomous Agents While Governance Lags Far Behind

By: TechVanguard – SeaPRwire – Sixty-one percent of leaders expect most AI agents to run largely on their own within four years. Only twenty-one percent say their organizations can redesign the processes that will surround them. The gap sits right there in the Deloitte numbers from August 2026. Five hundred one senior managers and executives in the United States answered the survey. The ambition is clear. The readiness is not.

Seventy-four percent expect nearly half of their business processes to be rebuilt around AI agents in the same four-year window. Just five percent call their current processes highly prepared for autonomous AI. Only fifteen percent have scaled coordinated agents across multiple functions. An AI agent can already push multi-step workflows toward a goal. It can talk to external software without waiting for human approval on every step. That shifts the employee’s role. Policies must therefore spell out access privileges, escalation points for human review, quality-control steps, and who owns the error when something breaks.

Okta’s May 2026 numbers sharpen the same problem. Ninety percent of security leaders feel confident they can see organizational AI use. Fifty-two percent of knowledge workers still run unapproved tools without IT or security sign-off. Fifty-eight percent of executives reported an AI-related security incident or close call in the prior twelve months. The visibility gap and the incident rate sit side by side. Explicit controls of the kind already applied to human employees become the next requirement.

Azahara Corrales, an AI governance strategist interviewed in August 2026 by Lorka AI, pointed to another missing piece. Front-line staff understand the procedural nuances. They are best placed to mark which tasks an agent can handle alone and which decisions must rise to a person. Before any expansion of agent duties, clear access levels, approval thresholds and review procedures have to be written down. Those guardrails decide whether people can still supervise the technology as their own roles change.

The survey data and the security findings point in one direction. Ambition for autonomy has moved ahead of the operational rules needed to contain it. Organizations that keep adding agent scope without those rules will keep meeting the same friction.

Write the access rules first.

Author bio: TechVanguard, social-media tech voice with a large following on X, focused on practical gaps between AI promises and workplace reality.


source https://newsroom.seaprwire.com/press-releases/technologies/companies-race-toward-autonomous-agents-while-governance-lags-far-behind/

Saturday, October 17, 2026

As-Built Plans Close the Loop: Estimators Who Skip Them Bid Blind Twice

By: James Vance – SeaPRwire – Field changes walk away unrecorded and the next bid pays for it. Estimating Edge just put out a guide that treats as-built plans as the fix. The company builds The EDGE estimating software and sits under Foundation Software. The new piece is titled “The Contractor’s Guide to As-Built Plans (and Why Estimators Need Them).” It shows what those final drawings actually capture and how estimators can turn them into sharper prices.

Official points stay tight. Construction almost never matches the blueprint exactly. When field changes stay off the record, contractors pay twice. Closeout and final payment stall first. The next bid then repeats the same misses. As-built plans are the final drawings that show the project exactly as it stands. Every change sits on them. That record gives a true account of what the job actually took. Each finished project then makes the following bid tighter. The guide walks through clear distinctions. As-built drawings differ from design drawings, shop drawings and redline drawings. Each type fits a different spot in the process. Four kinds of change land on every as-built set: dimensional shifts, utility routing, material substitutions and field obstacles.

Owners prefer the as-built set before they release final payment. Tying approved change orders to that same record keeps the estimate history accurate and usable later. Comparing the original estimate against the as-built data reveals where material quantities, labor hours and substitutions moved the final cost. Those comparisons stack up over multiple jobs. Estimators who review the data project after project start to see repeating gaps. One common gap is underestimated labor on a certain scope. Another is a material that gets substituted on almost every job. Once the pattern shows, the next bid can adjust before it goes out.

The EDGE software has served commercial construction takeoff and estimating for roofing, fireproofing, interior and exterior finishing trades for more than thirty years. Foundation Software adds job-cost accounting, expense and pay tools, project management, safety, HR, mobile field apps and payroll. The new guide simply points estimators back to the one record that already exists on every finished job. Use it or keep paying the same misses twice.

Author bio: James Vance, technical director and geek analyst with deep experience inside major Silicon Valley platforms, focused on industrial data systems and real-time production tools.


source https://newsroom.seaprwire.com/press-releases/technologies/as-built-plans-close-the-loop-estimators-who-skip-them-bid-blind-twice/

Friday, October 16, 2026

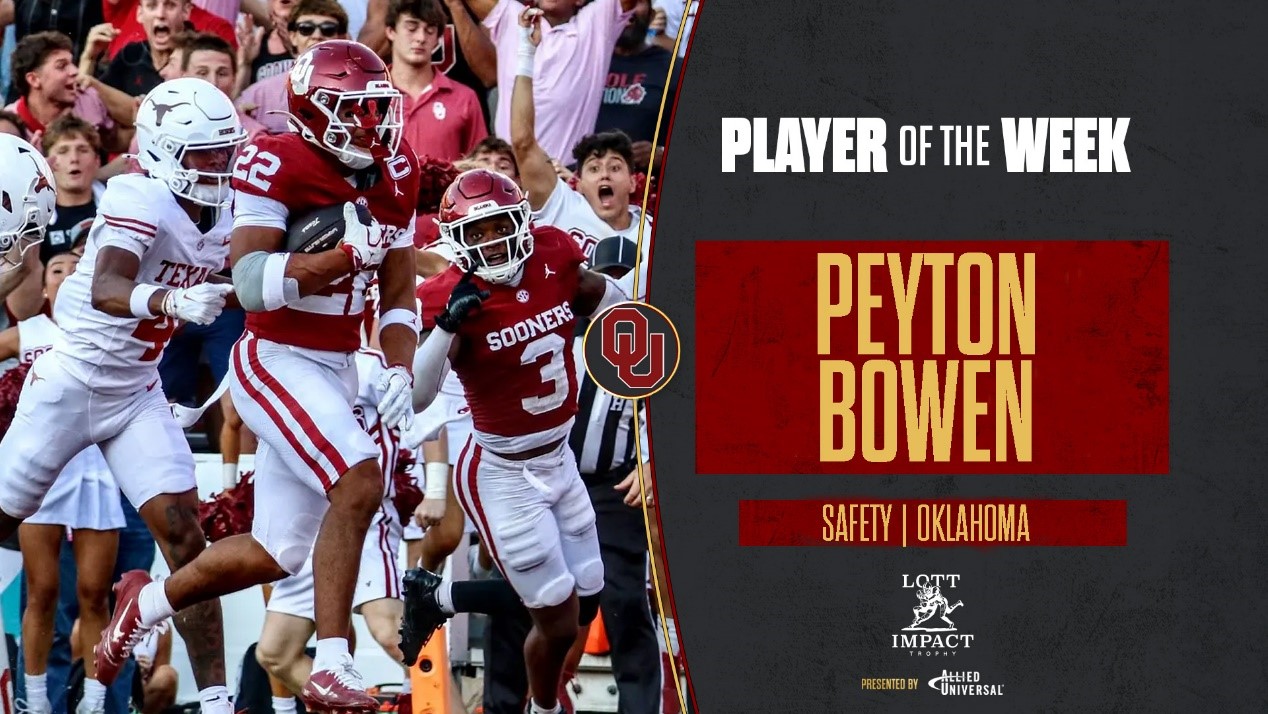
Pick-Six in the Red River: Oklahoma Safety Claims the Week 6 Lott IMPACT Nod

By: Logan Pierce – SeaPRwire – The release calls it Player of the Week. Strip the polish and the core is simple. A senior safety from Corinth, Texas, turned one play into the weekly award. Peyton Bowen of Oklahoma intercepted a pass and ran it back forty-two yards for a touchdown. He added seven tackles, six of them solo. The Sooners beat number one Texas twenty-seven to twenty-four in the Red River rivalry. That interception was the third of his career.

The vote process sits plain in the announcement. Former players, coaches and Lott IMPACT Trophy board members cast an internal ballot. Fans add a social media vote. Bowen cleared both. Last season the league coaches put him on the All-SEC second team. The SEC Fall Academic Honor Roll listed him each of the past two seasons. Those lines match the award’s own checklist. IMPACT stands for Integrity, Maturity, Performance, Academics, Community and Tenacity. The academic honor rolls cover the A. The pick-six and the tackle count cover the P.

Three other names appeared on the same weekly shortlist. Xavier Gilliam, sophomore defensive tackle at Tennessee, recovered a fumble and recorded a sack among one point five tackles for loss. He finished with four total tackles in the Volunteers’ twenty-four to seventeen win at Arkansas. Tre Miller, senior cornerback at North Carolina, intercepted a pass, broke up two more and made four tackles, two solo, in the Tar Heels’ twenty-one to seventeen win at Pitt. Jalen Woods, senior linebacker at UCLA, recovered a fumble, led the Bruins with nine tackles, four solo, and two for loss in a seventeen to fifteen upset at Oregon. Each posted a clear defensive mark. None matched the combination of a touchdown return and a ranked-team victory that Bowen delivered.

Allied Universal presents the trophy. The company calls itself the world’s leading security and facility services provider. It serves more than four hundred of the Fortune five hundred. Operations run in over one hundred countries and territories. It ranks as the third-largest private employer in North America and seventh in the world. Annual revenue sits near twenty-three billion dollars. The firm supplies AI-enabled security technology, integrated systems, monitoring and response. The weekly award and the December ninth final announcement in Newport Beach, California, keep the brand visible through the season.

The final 2026 Lott IMPACT Trophy winner will be named on December ninth in Newport Beach. Until then the weekly selections keep the ledger current. Bowen’s numbers from the Red River game now sit at the top of that ledger for Week 6.

Author bio: Logan Pierce, independent business writer active on Medium and similar platforms, focusing on how sponsorships and weekly awards shape commercial visibility in college athletics.


source https://newsroom.seaprwire.com/press-releases/finance/pick-six-in-the-red-river-oklahoma-safety-claims-the-week-6-lott-impact-nod/

Thursday, October 15, 2026

Scatter, Foam, and Less Waiting: Maxon’s 2027.0 Update Actually Moves the Needle for Working Artists

By: TechVanguard – SeaPRwire – Most software updates promise the moon and deliver a checkbox. Maxon’s Fall 2026 release, shipping the 2027.0 versions of Cinema 4D, ZBrush, Redshift, Red Giant and Autograph, feels different. It targets the exact friction points artists complain about in daily production. Bigger environments. Faster feedback. Fewer app switches. That is the real pitch.

Look at the official list first. Cinema 4D 2027.0 adds a full Scatter System. The new Scatter Generator and Scatter Tag handle distribution, filtering, clustering and transforms. They plug straight into MoGraph Fields and Effectors so artists can shape and animate the scatter without leaving the familiar toolset. Liquid FX joins the unified simulation system. Foam, spray and bubbles generate automatically from the liquid and respond to its motion. The release also tightens the Cinema 4D–Redshift link, improves ACES 2.0 alignment and adds everyday quality-of-life fixes. ZBrush gets a native UV Editor built on Cinema 4D technology. It supports UDIMs and texel density so artists can create and refine UVs without exporting. Selection Sets let users save and recall Polygroups, masks, Polypaint, morph targets and UV layouts. On iPad, Spotlight arrives for reference and projection work. Non-destructive 3D Layers let artists experiment with sculpting, polypaint and masking without locking changes. Redshift reworks its memory architecture for better efficiency across hardware. Interactivity jumps so changes to lights, materials or scene elements show up faster. Artists can drag Cinema 4D objects, Cloners and particle systems straight into material workflows and the Node Editor. A new procedural system generates fur, fibers, textiles and knitted materials at render time. NVIDIA RTX Spark support expands the hardware range. Red Giant adds Scene Light, an AI-powered depth-aware relighting tool inside After Effects. Artists place interactive lights for muzzle flashes, explosions or day-for-night shifts and keep them art-directable. Maxon Noise comes to Universe. Real Lens Flares gains Custom Schmutz for personal grime textures and more Light Source Types. Chromatic Displacement lands in Autograph. Maxon Studio Capsules get richer Custom UI controls. Autograph itself gains an MCP Server that links AI agents to its native tools. Artists can now copy and paste 3D elements, including animation, cameras, lights, nulls and primitives, directly from Cinema 4D into Autograph. Everything ships on 14 October 2026.

Now the practical reading. Artists have asked for proper scattering inside Cinema 4D for years. The new system answers that request with MoGraph integration instead of forcing a separate plugin or heavy workaround. Liquid FX removes the need to build secondary foam and spray sims from scratch. In ZBrush the UV Editor and Selection Sets cut the constant back-and-forth that slows iterative sculpting. iPad gains layers and Spotlight so the tablet stops feeling like a sketch pad and starts feeling like a production station. Redshift’s memory and interactivity work hit the moment artists care about most: the gap between a change and the next preview. Dragging Cloners and particles into materials removes busywork. Procedural fur and textiles at render time keep the scene lighter. Red Giant’s Scene Light gives compositors real control over interactive lighting without heavy masks. Maxon Noise and Custom Schmutz put familiar procedural and grime tools where motion designers already work. The Autograph MCP Server and the direct Cinema 4D paste link start closing the gap between 3D and compositing. CEO David McGavran framed it as listening to artists and stacking capabilities so the possible keeps expanding. A few years ago liquid simulation in Cinema 4D could not pour a beer with foam and spray. Now it can. That is the concrete progress the release claims.

The pattern across the suite is clear. Maxon is reducing the number of times an artist has to leave the current app or rebuild something by hand. Scatter and Liquid FX stay inside Cinema 4D. UV work and selection management stay inside ZBrush. Faster Redshift feedback stays inside the render loop. Scene Light and Maxon Noise stay inside the compositing timeline. MCP and the Cinema 4D paste stay inside Autograph. The result is fewer barriers between idea and final frame. Artists who live in these tools every day will feel the difference first on dense environments, fluid shots, complex sculpts and interactive lighting passes. The ones who still juggle five apps for the same tasks will notice the friction more sharply.

This is how production pipelines tighten. Not with one flashy feature, but with a set of targeted removals of daily drag. The 2027.0 tools are available now. The practical test is simple: open a current project that still needs external scatter, secondary fluid sims or repeated UV rebuilds and see how many of those steps disappear.

Author bio: TechVanguard, a veteran technical director and tool analyst who has spent years inside large-scale VFX and animation pipelines across major studios.


source https://newsroom.seaprwire.com/press-releases/technologies/scatter-foam-and-less-waiting-maxons-2027-0-update-actually-moves-the-needle-for-working-artists/

Wednesday, October 14, 2026

Supertab on Fastly: Classify the Bot, Publish the RSL Terms, Charge or Block at the Edge

By: Alex Mercer – SeaPRwire – Publishers on Fastly just got a third option. They can identify the AI crawler, publish machine-readable licensing terms, and decide per company whether to allow, block or charge. No CDN swap. No new origin infrastructure. Bots already exceed 49 percent of traffic. Most of that traffic pays nothing. That is the pressure point.

Official release facts are clean. Supertab announced on 12 October 2026 from New York that Supertab Connect is live on Fastly Compute. Publishers can classify AI bot traffic, publish RSL licensing terms, and allow, block or charge individual crawlers at the edge. Fastly already serves a large share of media companies, publishers and content platforms. Activation runs through Fastly Compute. The same product stays compatible with other major CDNs, the WordPress plugin and the SDK. Fastly’s Threat Insights 2026 report states bots now make up more than 49 percent of all traffic. Most of that volume generates no revenue for the publishers whose work is consumed. The traffic still costs infrastructure load, bandwidth and server capacity. Taking no action means giving the work away for free with no visibility into use. Simon Wistow, Fastly co-founder and VP of Strategic Initiatives, said Fastly has always focused on speed and protection and is now extending that to the economics of content access. Publishers should not have to choose between being crawlable and being compensated. The company has worked with publishers, standards bodies, partners, legislators and AI companies so sites can stay discoverable without going out of business. Cosmin Ene, Supertab founder and CEO, noted that the next audience is not entirely human. Bots, agents and AI systems already access content at scale. Supertab gives Fastly publishers a straightforward way to attach terms to that access. Classification identifies crawlers by the company behind them—OpenAI, Anthropic, Perplexity, Google—and by activity type, from training-data collection to agents fetching pages on a user’s behalf. Licensing terms use RSL 1.0, an open standard that lets publishers post machine-readable AI terms on their own domain. Supertab Connect publishes those terms and checks every crawler request against them at the edge. Access is enforced by the Crawler Authentication Protocol. CAP validates the crawler’s license token before the request reaches origin. Licensed requests are allowed and recorded. Unlicensed requests are blocked and pointed to the publisher’s terms. Human visitors pass straight through. Deployment requires no DNS changes. Typical time is two to three hours.

Industry subtext sits next to those numbers. Until now the practical choices were binary: block every AI crawler or let every one through. Blocking also cuts legitimate, revenue-generating traffic. Letting everything through leaves no terms, no data and no revenue. The Fastly integration places the decision at the edge, before origin, with real network reach. Every licensed request becomes an auditable record of exactly what each AI system consumed. Publishers set the terms. Fastly and Supertab apply them. The result turns previously invisible, uncompensated traffic into metered and potentially paid traffic. Supertab describes itself as infrastructure for consumption-based commerce. Connect classifies automated traffic by operator and activity. The licensing layer publishes RSL 1.0 terms on the site owner’s domain. The same layer meters, prices and settles usage across humans, agents and enterprises so that what machines consume can be measured and paid for as it happens.

The practical close is immediate. Any publisher already on Fastly can enable the SDK, publish RSL terms and start deciding per crawler today. Free trial and integration guide are live at supertab.co. Operators still running the old binary of block-all or allow-all can stop leaving the majority of traffic unpriced. That is the next move.

Author bio: Alex Mercer, a Silicon Valley tech director and edge-systems analyst who has spent years inside CDN policy, bot classification and content-licensing infrastructure.


source https://newsroom.seaprwire.com/press-releases/technologies/supertab-on-fastly-classify-the-bot-publish-the-rsl-terms-charge-or-block-at-the-edge/

Tuesday, October 13, 2026

Diesel Deal as Wedge: Washington Buys Russian Fuel After Threatening Others for the Same

By: Alistair Kroon – SeaPRwire – Washington just became a customer for Russian diesel. Weeks earlier it threatened 100 percent secondary tariffs on anyone else who did the same. Allies call it a wedge driven into the coalition core. India calls it open hypocrisy. The volumes are small. The diplomatic signal is not.

Official statements fix the numbers and the sequence. On 9 October President Trump announced agreement with President Putin. Russia would supply more than 300,000 tons of diesel immediately to the United States and global markets, 500,000 tons in November, then another 1 million tons, and up to 3 million tons shortly thereafter depending on Russian refining conditions. The arrangement pauses sanctions on Russian energy exports for six months and allows sales at market prices. On 18 September Trump had signed the 2026 Graham Sanctions on Russia and Iran Act. That law permits secondary tariffs of up to 100 percent on third countries importing Russian oil or gas. Trump also declared an immediate “energy ceasefire.” Neither side would attack the other’s energy facilities. He warned Ukraine not to strike Russian refineries because that would create global problems. Ukrainian President Zelenskyy told American media he learned of the energy ceasefire from news reports. If Russia agreed, Ukraine would agree. He asked for a 60-day ceasefire so Ukraine could hold elections. Russian Foreign Minister Lavrov replied that Zelenskyy does not deserve a breathing space on the battlefield. Inside the United States seven senators, including four Republicans, issued a statement demanding the administration abandon the plan and calling it illegal. Senate Democratic leader Chuck Schumer said the move was designed to rescue Trump’s political standing. Supporters argued the deal would help lower domestic fuel prices. Republican Senator Barrasso described it as a difficult choice that could also serve as leverage for a longer-term solution.

Geopolitical reactions landed hard. Indian media and scholars labeled the purchase naked double standards. The United States had repeatedly pressured New Delhi over Russian oil purchases, including punitive tariffs and the threat of 100 percent secondary duties, while claiming such purchases fund the war. When American diesel prices became a domestic concern, Washington green-lit its own imports. Indian outlets asked why American purchases are acceptable while Indian purchases invite punishment. European allies criticized the unilateral step as breaking shared sanctions architecture. Germany’s Alternative for Germany co-chair Alice Weidel called the deal pragmatic Realpolitik and said Germany should pursue a similar arrangement to cut domestic energy costs. German left parties voiced comparable views. Chancellor Merz ruled out any such move. On 12 October the European Union added roughly 1,600 Russian individuals and entities to its sanctions list. Russian analysts noted the volumes are too small to move American pump prices meaningfully yet still ease Moscow’s fiscal pressure and shift the negotiating climate. RT described the agreement as the first practical result of direct U.S.-Russian contact and a diplomatic nightmare for Ukraine, proof that Washington and Moscow can reach deals without Kyiv.

The pendulum has already swung. Energy pragmatism replaced sanctions rhetoric for this cargo. The six-month pause and the energy-ceasefire claim sit on the table together. Allies who absorbed the economic cost of earlier sanctions now watch Washington act alone. The practical next step for any capital still bound by the old consensus is to decide whether the diesel precedent is a one-off election-season exception or the start of selective enforcement. That decision will set the real price of the agreement far more than the tonnage itself.

Author bio: Alistair Kroon, a veteran geopolitical commentator whose columns appear in major international newspapers and focus on energy sanctions, alliance cohesion and great-power bargaining.


source https://newsroom.seaprwire.com/contributors/alistair-kroon/diesel-deal-as-wedge-washington-buys-russian-fuel-after-threatening-others-for-the-same/

Tidal Wave’s Twin Openings: Free Washes, $10 Club Entry, and Two Local Givebacks

By: Logan Pierce – SeaPRwire – Two new Tidal Wave sites open in the same week. One in Claremore, Oklahoma. One in El Paso, Texas. Free premium washes run for twelve days. A $10 Founders Club deal locks new members into thirteen months of savings. Local schools and disability programs get the cash. That is the play.

Official announcement facts are precise. The release is dated 9 October 2026 from Thomaston, Georgia. Tidal Wave Auto Spa opens locations this week in Claremore, Oklahoma and El Paso, Texas. The Claremore site is the company’s sixth in Oklahoma. The El Paso site is its twenty-third in Texas. The full network now stands at 335 locations across thirty states. Both sites offer twelve days of free premium washes from 7 October to 18 October. The free option is Graph-X4® + Super Shammy. Standard features include mat cleaning stations, complimentary tire air, spot-free rinse, undercarriage wash, foam and wax treatments, and tire shine. The Founders Club offer is extended through the same dates. New members on the top three wash plans pay $10 for the first month, then receive $10 off each of the next twelve months. That equals thirteen months of savings. Membership grants access to the entire 335-location network. CEO and founder Scott Blackstock stated that opening both markets in one week reflects current growth into new areas and deeper presence in existing ones. He described Claremore as a community with strong identity and loyal roots. He called the second El Paso location a direct response to local embrace. Tidal Wave has donated more than $8 million to charitable organizations nationwide. Claremore Giveback Day is set for 14 October from 9 a.m. to 6 p.m. The company will donate $1 for every free wash and $5 for every new Clean Club membership to Roosa Elementary School. Funds support academic excellence and STEM education. The school is one of the few in Oklahoma consistently recognized as a Great Expectations Model School. El Paso Giveback Day is 15 October, same hours. The same donation formula goes to The ARC El Paso. Funds support inclusion of people with intellectual and developmental disabilities. Claremore address is 1701 Scissortail Ave, Claremore, OK 74017. El Paso address is 1458 Lee Trevino Drive, El Paso, TX 79936. A nearby existing El Paso site is at 2080 N Zaragoza Rd. Additional openings are planned this year in Albuquerque, New Mexico and Merritt Island, Florida. Single washes start at $15. Unlimited memberships, family plans and fleet plans are available. The company was founded in 1999 in Thomaston, Georgia by Scott and Hope Blackstock. It began as a small-town self-service wash, became the first conveyor car wash in Georgia, and is now the fifth-largest conveyor car wash company in the nation.

Commercial intent is straightforward. Free premium trials pull traffic. The $10 Founders Club entry converts that traffic into multi-month recurring revenue while giving members network-wide access. Local Giveback Days turn the same traffic into community goodwill and measurable donations. The dual-market timing tests both new-market entry and densification in a proven city. The $8 million cumulative charity figure is the long-term proof of the same model. Brands that open without a trial-plus-membership-plus-local-donation stack leave volume on the table. Tidal Wave put the full stack on the calendar for both sites this week. Operators watching the sector can copy the same twelve-day free window and thirteen-month club math.

Author bio: Logan Pierce, a veteran operator with decades of front-line experience scaling multi-unit service businesses across retail and franchise formats.


source https://newsroom.seaprwire.com/press-releases/finance/tidal-waves-twin-openings-free-washes-10-club-entry-and-two-local-givebacks/

Monday, October 12, 2026

ZHILAI MED’s RFID Loop: 97 Percent Traceability, One Staffer for a 3000-Staff Hospital

By: Alex Mercer – SeaPRwire – A closed-loop RFID system for hospital workwear and linen just claimed 97 percent traceability. One delivery worker now covers morning restock and afternoon collection at a 3000-staff site. Staffing for that task dropped 80 percent. That is the number that matters. Manual counts and single-barcode scans cannot match it.

Official release facts list the full stack. ZHILAI MED announced an RFID-powered smart textile management solution on 10 October 2026 from Shenzhen. It targets healthcare facilities and industrial laundries. The goal is better traceability, efficiency and digital control of workwear, uniforms, linens and other reusable textiles. The system combines RFID identification, automated workwear dispensers, return units, laundry inventory tools and cloud software. Together they form a closed loop. Every textile item receives a unique RFID identity. It is tracked from registration through distribution, use, return, washing, inventory and reissue. RFID reads multiple items at once. Manual records or barcodes require one-by-one scanning. The difference gives clearer visibility into circulation and stock levels. The Automatic Workwear Dispenser holds up to 500 uniforms. Authorized staff get 24-hour self-service access. Authentication works by facial recognition, staff cards, QR codes or passwords. Low-inventory alerts flag when stock runs short. The Return Unit pairs RFID with infrared detection. It identifies returned garments in under three seconds. The unit occupies roughly 0.6 square meters. Compact size suits tight healthcare spaces. It also detects metal objects inside returned workwear. If metal is present the compartment stays locked. That step cuts hospital asset loss and shields laundry staff from hazardous items. The cloud platform shows real-time inventory and movement data. It links to existing hospital staff-card or HR systems. It logs status and history for each textile piece. It produces department-level washing and cost reports. In project deployments the solution reached a 97 percent textile traceability rate. One hospital with about 3000 staff needed only a single delivery employee for morning restocking and afternoon collection. Related staffing requirements fell by 80 percent. The system is already live in more than 200 healthcare institutions. Hong Kong sites include Queen Mary Hospital, Pamela Youde Nethersole Eastern Hospital and Kowloon Hospital.

Industry subtext sits next to those figures. Laundry and workwear still run on paper lists or slow barcode lines in many hospitals. RFID bulk reads and automated dispensers remove that friction. The metal-detection lock on the return unit addresses a concrete hospital risk. Asset loss and needle-stick hazards for laundry crews are real costs. The cloud layer turns every wash cycle into department cost data. That report is what finance teams actually use. ZHILAI MED is a subsidiary of ZHILAI Technology. Manufacturing sits in two bases, one in Xianning, China, and one in Binh Duong, Vietnam. Annual capacity exceeds 200,000 units. Production is fully automated and lean. The parent offers OEM and ODM services worldwide. The company will show the dispenser, return unit and full management suite at EXPOdetergo International 2026 in Milan. Dates are 23 to 26 October. Location is Hall 03, Booth G26.

Supply-chain reality for this class of hardware is straightforward. High unit volume and dual-country production keep the cost base low enough for hospital budgets. Deployments already past 200 sites prove the loop works outside the pilot stage. Hospitals that still count textiles by hand can start with the same dispenser-plus-return pair that cut staffing 80 percent at the 3000-staff site. That is the practical next step.

Author bio: Alex Mercer, a Silicon Valley tech director and systems analyst who has spent years inside RFID deployments, automated logistics hardware and hospital operational tech.


source https://newsroom.seaprwire.com/press-releases/technologies/zhilai-meds-rfid-loop-97-percent-traceability-one-staffer-for-a-3000-staff-hospital/

Sunday, October 11, 2026

Epomaker HE60 at Sixty Bucks: Magnetic Speed, Built-In Thock, No Extra Desk Real Estate

By: Alex Mercer – SeaPRwire – Sixty percent layout. Hall Effect magnets. Factory thock. Fifty-nine ninety-nine. Epomaker just dropped a board that packs competitive tools into a footprint most FPS players already clear for mouse swings. The price sits low for what the spec sheet lists. That gap is the real signal.

Official release facts start clean. The HE60 is a 60 percent Hall Effect gaming keyboard. It pairs ultra-precise control with immersive sound and flexible wireless links. Compact design frees desk space and opens more room for mouse movement. FPS players who need wide, fast mouse arcs get the direct benefit. Two-stage feet appear on the board. Those feet are rare on magnetic keyboards. Users can set the typing angle to match posture. Long sessions stay more comfortable. Factory-lubed Creamy Jade Hall Effect magnetic switches sit inside. The feel is responsive with a slightly firm press, strong rebound, and clear feedback. Rapid Trigger adjusts down to 0.005 mm precision. Players tune key response to their own habits. Faster reactions and steadier control follow in high-intensity play. DKS and SOCD expand the customization set. Key behaviors can be optimized for competitive cases. Wired and 2.4 GHz modes both push high-speed input. Every movement and command registers quickly.

Industry subtext sits right next to those numbers. A sixty-dollar magnetic board that ships with Rapid Trigger at that resolution and dual 8000 Hz paths is not the usual entry price. Most magnetic boards still ask more for the same feature set. The five-layer dampening stack, tray-mount structure, aluminum positioning plate, and tuned internal filling are listed as the source of the fuller, concentrated thocky profile. No extra mods required. That claim lands because the switches and the acoustic stack are named together. Connectivity covers Bluetooth, 2.4 GHz, and USB. Wired and 2.4 GHz both hit 8000 Hz polling. An 8000 mAh battery handles the higher draw common to magnetic boards and still claims extended wireless time. Black and white colorways ship now. The gaming-inspired ribbon design adds visual character and makes the board easier to carry. Availability is live on the Epomaker official site, Amazon, and AliExpress. Official-site price is locked at 59.99 dollars. The company describes itself as Epoch of Makers. Its stated focus is distinctive sound, thoughtful customization, and performance. The team mixes gamers, software engineers, product designers, and mechanical keyboard enthusiasts.

Supply chain reality for this class of board is simple. Magnetic switches, aluminum plates, multi-layer dampening, and high-poll rate wireless all carry cost. Shipping a finished unit at under sixty dollars means the margin lives in volume and in skipping the usual aftermarket sound kit. The HE60 puts the full list on the table at that price. Buyers who need compact desk space, adjustable Rapid Trigger, and ready thock can stop at the official page and order. That is the practical close.

Author bio: Alex Mercer, a Silicon Valley tech director and hardware analyst who has spent years inside keyboard firmware, magnetic switch validation, and competitive peripheral design.


source https://newsroom.seaprwire.com/press-releases/technologies/epomaker-he60-at-sixty-bucks-magnetic-speed-built-in-thock-no-extra-desk-real-estate/

Saturday, October 10, 2026

Five Liters, Not Five Hundred Bottles

By: Christian Brooks – SeaPRwire – Premium water in the United States still arrives mostly in single-serve plastic. A Finnish brand is betting that larger bag-in-box formats and a low-mineral profile can change the daily habit. The product is already on OneLavi.com. Amazon availability is next. That listing will decide whether the format travels beyond early adopters.

On 9 October 2026 NWB Finland Oy announced from Boca Raton that AINA Natural Water is coming soon to Amazon. The move continues the company’s planned U.S. rollout. AINA first became available to American consumers through OneLavi.com. Marita Weiman, Quality Assurance Manager at NWB Finland Oy, called the Amazon expansion an important next step. The goal is to make discovery and purchase easy while introducing what makes Northern Finnish water and the packaging approach different. The water originates in the Pudasjärvi region of Northern Finland. Groundwater is naturally filtered through layers of soil, sand and rock, then mechanically filtered and packaged. It contains approximately 32 mg/L of Total Dissolved Solids. The low mineral content produces a soft, neutral taste and a clean finish with no aftertaste. Instead of individual plastic bottles the brand offers 5-liter and 10-liter bag-in-box formats intended for home, work and other everyday settings. The packaging uses substantially less plastic than comparable volumes sold in traditional single bottles. NWB Finland Oy presents three differentiators for the U.S. market: the Northern Finland source, the naturally low mineral profile, and the sustainability-focused packaging. The company recently participated in the 2026 ECRM Vitamin, Weight Management & Sports Nutrition Session in Palm Beach Gardens, Florida, where AINA and its bag-in-box format were shown to U.S. retail buyers. Weiman said the U.S. presence is being built step by step and that Amazon will significantly broaden the opportunity for consumers across the country. The brand lists its points of difference as the Northern Finland source, natural filtration, measured purity at roughly 32 mg/L TDS, a clean taste profile, naturally low sodium, and packaging that reduces plastic relative to bottled formats. Further Amazon details will be released when the product becomes available for purchase. NWB Finland Oy is a Finland-based company focused on sustainable beverage packaging and natural water solutions, headquartered in Pudasjärvi. Its flagship brand is AINA Natural Water. The long-term vision is to make Northern Finland’s groundwater available to consumers globally while continuing to invest in sustainable packaging.

The commercial filter is simple. Watch the moment the Amazon listing goes live. Watch the early review volume and the share of 5-liter versus 10-liter units that sell. Those two signals will show whether the bag-in-box format converts curiosity into repeat household use.

Author bio: Christian Brooks, financial and business commentator focused on beverage packaging innovation and direct-to-consumer grocery expansion.


source https://newsroom.seaprwire.com/press-releases/finance/five-liters-not-five-hundred-bottles/